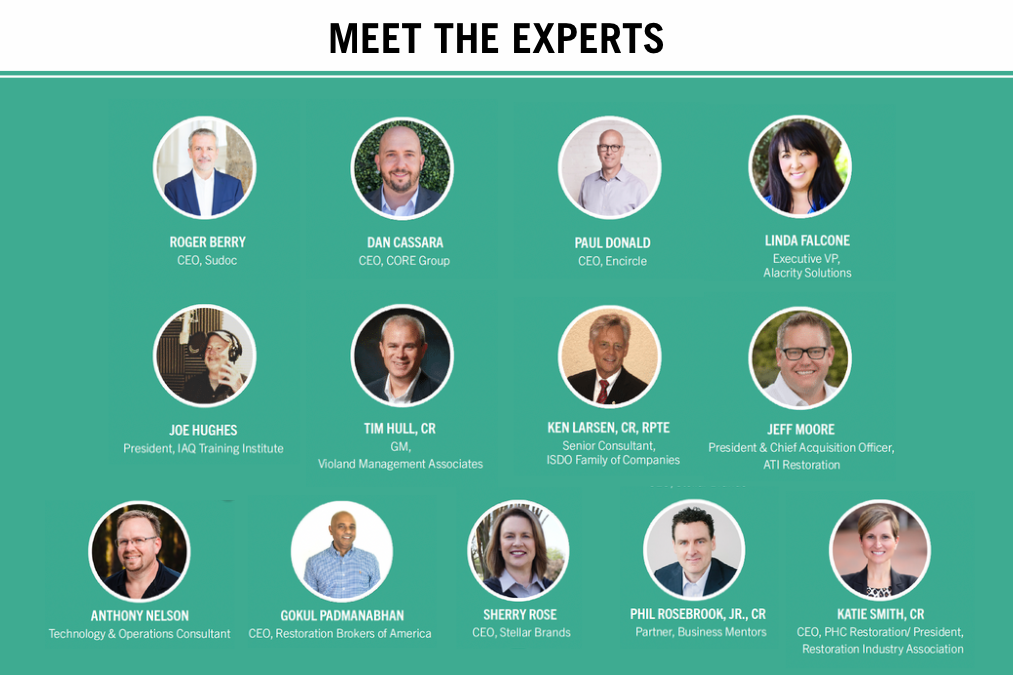
Publisher’s Note: To enhance the 2022 C&R State of the Industry Study, we brought in 11 experts from a number of corners of the cleaning and restoration industry to answer two questions: what do you see as our industry’s biggest strength and weakness? And what should contractors being paying attention to in 2023? You’ll find answers related to pricing and profitability, product choice and sustainability, industry involvement, drying, insurtech, carriers and TPAs, and more!
1. WHAT DO YOU SEE AS OUR INUSTRY’S BIGGEST STRENGTH AND WEAKNESS?
BERRY: We think the greatest strength of the restoration and remediation industry is the ability to respond rapidly to people in times of crisis and uncertainty. This really is an industry of everyday heroes steadfastly providing solutions to problems that can be overwhelming and debilitating for individuals. An improving focus on education and training is moving us forward to a future that is solidly rooted in science and value. A weakness the industry needs to address is the amount of chemicals we are bringing to people’s homes—we need to find a better balance and develop solutions that are highly effective but leave behind less chemical burden.
CASSARA: In terms of the industry’s biggest strengths, I would say we are in a recession proof, pandemic proof, incredibly resilient industry and our biggest strength is that we are not only an essential industry but one that will be very difficult to eliminate through technology and innovation. Restoring people’s lives is something that must be handled by the experts of our industry and cannot be replaced with technology.
DONALD: The restoration industry has never in its history been more important to local and national economies than it is today. That said, the reporting requirements by insurers and managed repair networks, data-driven organizations dependent on restorers, is putting significant operational cost pressure on this critical industry to the point where many restorers wonder whether they can continue serving their communities. My peers say I have a good grasp of the obvious as this shouldn’t come as a surprise to anyone.
FALCONE: The insurance industry’s biggest strength is that we are not as affected by political, economic, or world crisis as much as other industries. Claims still occur when any or all these factors are in play. While insurance companies cannot control the claim activity, they can control their loss ratios by working with TPAs to take pressure off the adjusters and controlling costs while making it a better experience for their customers. The insurance industry’s biggest weakness is the loss of veteran adjusters retiring. The incoming adjusters are few and not experienced to manage the load.
HUGHES: From my somewhat outside perspective, reliance on insurance work is the industry’s biggest strength and weakness. Insurance work has advantages and disadvantages and your readers know them well, or should. Property insurance is unique in some ways but like all insurers, they have to make money or go out of business. Rates will be going up dramatically in some areas, and coverage may not be available at least at rates homeowners can afford. Diversify so that if the insurance work dries up, you will still be in business. Don’t put all your eggs in one basket.
HULL: During our podcast, I mentioned a couple of the strengths and weaknesses of the industry right now with a looming recession being on the top of everyone’s mind. While this is certainly something to pay attention to, I believe that the immediate impacts of inflation on the supply chain and workforce are a more immediate concern. This has increased direct and indirect job costs for restorers at a rate that out paces the market price for their services. The result is shrinking margins and bottom lines. Fortunately, the demand for services remains high, but that will wax and wane with seasonal cycles for different parts of the country. As it does, contractors will be forced to focus their efforts on process improvement initiatives to increase margins to normal levels. One of the biggest trends we see in this arena is with the use of technology to automate business processes. Critical functions like marketing, estimating, invoicing, and material procurement are leading the list of these initiatives.
LARSEN: Billions of dollars of insurance money are spent repairing water damaged structures every year! They are not all restored identically. It depends largely on how contaminated the water is. Each of these claims relies heavily on correct categorization of water.
MOORE: The Restoration Industry Association (RIA) is our industry’s biggest strength and also its biggest opportunity. The RIA is crushing it with its advocacy work. RIA’s Advocacy and Government Affairs Committee (AGA) and Pricing Advocate, Ed Cross, are boosting restorers’ bottom lines. We have incredible leaders represented on the board and committees. The top restoration instructors in the world teach RIA classes. The opportunity we have is RIA membership. Only 10% of all restorers are currently members of our trade association. For the RIA to have the resources, capital and volunteers to move the needle for our industry, we need more restorers to join the RIA in 2023. Regarding weaknesses, the U.S. government does not define restoration as a trade. The North American Industry Classification System (NAICS) was developed for use by federal agencies to collect, analyze and publish statistical data by industry. Because restoration does not have its own unique NAICS code, it’s impossible to accurately quantify, track, or analyze the work we do, thus fragmenting what is seen in the public record. This affects everything from government contracts to tax incentives. Until we have a primary NAICS code for disaster recovery services, determining anything and everything about our industry is impossible. Let’s also quickly discuss pricing. Inflation rates are out of control, impacting our supplies, materials, and equipment. Most pricing platforms cannot keep up in real time. No matter the platform you use to estimate or price jobs, it’s vital that it be up to date.
NELSON: The industry’s biggest strength is its people and their determination, drive, and sincere desire to make a difference for people, businesses,
and communities in their time of need. We literally move mountains to make the world a better place. Our greatest weakness is that a majority of the individuals in the business of restoration have a lack of focus on the business and creating sustainable enterprises. We become victims to the rise and fall of our businesses instead of focusing on making them resilient and ever-lasting.
PADMANABHAN: From an M&A perspective, one of the biggest strengths is that we are somewhat of a recession-resistant industry. Our cashflow is insulated as far as those numbers are concerned. I don’t think we’ll feel as much pain in the really good companies – their valuations will hold steady. The negative is that buyer confidence is dropping, so if you’re not prepared when you go to market, you’ll experience up to a 12% decrease in your company’s valuation going forward. If you’ve built a quality business, you’ll see a good year in 2023. If you’re carrying a lot of debt, you could see trouble as the cost of debt increases.
ROSE: We have the unique privilege of delivering an essential service that has real and positive impacts on lives, livelihoods, and communities. We are the solution to damage and chaos, delivering a way back to normal to our customers and communities. Regarding weaknesses, it can be difficult to serve the customer when there are multiple parties involved in paying the bill.
ROSEBROOK: Restoration is a recession resistant. Work will continue regardless of fluctuations in the economy – whether it is recession or a covid shut-down, properties will still need repaired and insurance funding is stable. The added bonus is that restoration has a strong purpose – restoring lives and livelihoods in the event of a disaster. As the world turns to green solutions and focuses on reuse, reduce, and recycle, restoring properties is the ultimate green solution. Greatest weakness: There are few barriers to entry. As the economy slows, jobs will be lost to general contractors, carpet cleaners, janitorial companies, or client cash outs. Companies that have payroll and overhead will start taking jobs from the restoration pool.
SMITH: Restorers value relationships, and we have a desire to help. We view our peers as collaborators instead of competitors. We can put our egos aside and work together for the greater good, like the volunteers of the Restoration Industry Association are doing. The RIA’s advocacy initiatives are moving the needle in areas such as pricing, TPAs, legislative issues, and the adjuster/restorer relationship. We couldn’t do this without our biggest strength: the volunteers who are willing to leverage their relationships and share their knowledge and talents to unite the industry and advocate for the restorer. Weakness: Because our work is emergency-based, it’s easy to be distracted by the urgent and ignore the important, which leaves many restorers thinking they don’t have time to be concerned for the industry’s well being and sustainability. If we want to leave this industry better than we found it, we all need to get involved. The RIA’s Advocacy and Government Affairs team has made great progress with the support of a small percentage of U.S. restoration companies. Imagine what we could accomplish with everyone engaged! With our new dues model, RIA membership is the most accessible and affordable it’s ever been. Now is the best time to join!
2. WHAT WOULD YOU ENCOURAGE RESTORERS TO PAY ATTENTION TO IN 2023?
BERRY: We encourage restorers to adopt innovations in chemical usage and consumption. There is a growing demand by homeowners and other clients to be conscious of the health impacts of microbial growth but also the impacts of the chemicals used against them. Chemicals can impact human health and development, so we must find approaches that improve the quality of life for the worker and the homeowner alike.
CASSARA: I think the biggest weakness our industry faces is ego. So many restorers fail to realize there are solutions to help make their lives easier but often times I find that many restorers put their ego before the best interests of themselves and sometimes even their own people. That ego can be incredibly damaging and often times cause significant friction both to other restorers and customers, leaving people to feel like they don’t know who they can trust.
DONALD: For restorers in this industry to thrive, they need to embrace technology and technology-driven processes that support the data collection requirements imposed on them with the least amount of administrative burden. To deliver the full benefit to restorers, it requires collaboration and integration across several leading technology vendors serving this industry. I’m happy to say that 2023 will be the year when the restoration industry really starts to see the benefit of these collaborations and integrations on their operations. Restorers who engage with these technology providers and implement well thought through field documentation processes will see significant operational cost benefits and higher profits.
FALCONE: Since COVID, we have all had to pivot due to the changes caused by the pandemic. I would encourage restorers to pay close attention to the communication. Communication has always been important, however, with the labor shortages, product delays, and project timelines pushed out, we need to be diligent in over-communicating. Communication should be in the form of writing so timelines can be created around delays. Get creative and be informative when helping the insureds with their material selections. If they know up front there are delays on certain products, they may choose to go in a different direction to reduce the delays. Be consultative with the insureds throughout their project journey. We have found those who ask the customers, “how are we doing?” throughout their project will get higher satisfaction scores and they can proactively address any concerns before they become issues.
HUGHES: Infection control continues to be a huge issue and there are no miracle cures. We learned very little from the pandemic and cleaning for health’s importance will continue to rise to new levels.
HULL: While much of this may be burdensome in the short term, we can also view this as an opportunity to innovate and grow. Recent market consolidation has forced a significant amount of operating capital into the industry, which will change the competitive landscape in many local markets. In light of this, I would encourage contractors to be on the lookout for ways to vertically integrate complimentary services into their offerings. Larger enterprises and portfolio companies are already moving down this road and reaping the benefits with lower overhead costs and greater control through their production cycles. As this continues in the years to come, we could logically expect to see a smaller number of restorers to control a larger portion of market share. Smaller independent restorers will be forced to specialize in this scenario. However, this can also prove to be a profitable opportunity if they can effectively break dependencies on traditional referral relationships tied to vendor programs and third-party administrators. The biggest advantage they will gain is the ability to say no to less desirable work, freeing up resources already in short supply, to capitalize on higher margin work and less red tape.
LARSEN: S500-2021, §10.6.7 Preliminary Determination describes competent engagement of an Indoor Environmental Professional (IEP) to produce this category determination for the property owner. I predict contractors will be using IEPs more regularly as we realize Category 1 losses are the rarest of all water damage losses encountered. Contractors are tired of carrying the risk of incorrectly restoring contaminated structures due to insurer demands to comply with an insurance claims representative’s (or their consultant’s) speculative Category 1 restoration protocols and costs.
MOORE: Your # 1 asset is not your equipment, clients, or vendors, but your employees. To succeed and grow your business, you must invest to retain as many of your staff as possible. The quickest way to increase client revenue and referrals is to go above and beyond to keep every single employee. The money you invest will more than pay for itself in reduced costs for replacing personnel. Also, pay attention to technology and cashlow. I believe the future of estimating is relying more on technology and less on people in the field. Geospatial scans like Matterport and DocuSketch enable us to capture line items and write estimates remotely, efficiently, and accurately. Eventually, artificial intelligence will assist in generating scope and line items from a scan. Also, Xactimate’s pricing department is breaking from tradition and leaning toward pricing that’s predictive in nature. Improved pricing models are augmented by real-time feedback from trusted restorers, hand-picked and designated as certified pricing analysts by Verisk Estimating Solutions’ VP of Pricing, Greg Pyne. Making real-time pricing adjustments satisfies carrier demands for stability while maintaining credibility with the contractor community. With cashflow, every restorer, big or small, struggles with getting paid on time. A company called sureti is at the forefront of helping restorers collect payment faster and more efficiently while avoiding unnecessary complaints to carriers. As they evolve and grow, servicing more restorers, sureti will help our industry lower days outstanding.
NELSON: Pay attention to the markets where mergers and acquisitions have been very active. As an independent restorer, this will create opportunity. Once nimble and great organizations will become slaves to inapplicable and redundant processes, well-intended corporate demands, and general confusion. What works for one market doesn’t work for another. Both our customers and our employees are looking for more from us. Know your mission and values. Make compelling and different commitments in your marketplace to set yourself apart and remain disciplined in executing on those BEFORE ANYTHING ELSE. Stop being a victim to whether or not the phone rings and create the customer base and employee base yourself.
PADMANABHAN: There will be a challenging environment, so be offensive on lead generation and marketing and watch costs. If you’re going to market, you need to be prepared. There is a huge flight to quality and profits in the market, and those matter more than ever if you are preparing to sell your business. To reiterate, profits are going to matter now more than ever, so it’s vital that you are mindful of your costs. You absolutely have to prepare your business for sale before going to market if you’re going to get the right return on it.
ROSE: In a tough labor market, a healthy culture matters more than ever. Make sure your business is built around being a “talent magnet” that keeps your best people from leaving and attracts others who want to be a part of it.
ROSEBROOK: I think that there is a strong likelihood of a deep recession in 2023. This will lead to an increase in competition, increase in cash out offers, properties with equity challenges, and increasing cost of capital. Companies need to focus on efficiency, strategic planning, have an emphasis on marketing effectiveness, and strong collection procedures.
SMITH: Pay attention to the economic, social, and political landscapes and avoid the urge to run your business with the mindset that we are recession-resistant. While we may fare better than other industries, our clients feel the pain of economic downturns, which in turn can impact their spending behavior. Build reserves and be ready for the unpredictable. Pay attention to the AGA Academy content on the RIA’s website. It’s loaded with resources that can help improve your company’s documentation, estimating, negotiating, and collections processes.
Related Posts